
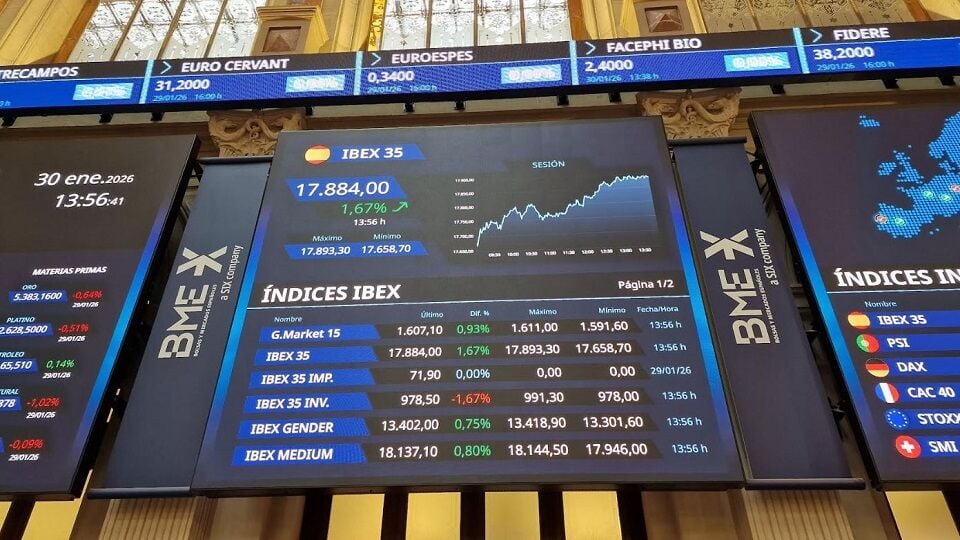
The Spanish stock market has experienced a month of January full of uncertainty and enormous volatility, even greater than that experienced in 2025, with Trump at the nerve center of everything. With a threat to Europe and Canada new tariffs on Greenland, Venezuela, oil, Iran and his nomination, today, of Kevin Warsh as the new president of the Fed, along with factors such as Japan’s debt, have had a high but positive impact on the market, which is how our country’s equities close the first month of the year.
Positive balance, more than positive actually, with up to 10 new historical highs, with which today it has broken its way to the 18,000 points that the Spanish selective already has within a stone’s throw. And with the banks as the true protagonists of this mechanism. And, as Araceli de Frutos, from Araceli de Frutos EAFI, told us today «as long as the banking sector continues to rise, the Ibex 35 will continue to rise, just as it has done with that 3.5% that it added in January.
The IBEX closes on Friday with gains of 1.66% to 17,880.90 points, with the advances of values such as Caixabank 6.75%, Banco Sabadell 3.93% and Solaria 3.05% and the falls experienced by Laboratorios Rovi 0.83%, Fluidra 0.57% and Inmobiliaria Colonial 0.48%.
Among the best, we find ArcelorMittal, Puig Brands B and Laboratorios Rovi so far this month, the last two very far behind, without remembering, in their stock market performance of the last year.
On the negative side of January, the cuts in values such as Mapfre, Amadeus and Inmobiliaria Colonial.
Already in the business news this Friday, without a doubt the main protagonist is Caixabank, with its large profits, skyrocketing the value today in the market after its good results at the end of last year.
The entity led by Gonzalo Gortázar achieved a net profit of 5,891 million euros in 2025, 1.8% more than in the previous year (5,787 million), “thanks to intense commercial dynamics, which favored strong business growth in a context of containment of interest rates, and to financial strength that was reinforced throughout the year.”
Furthermore, the Board of Directors of CaixaBank has approved at its last meeting to propose to the General Meeting of Shareholders the distribution of a complementary cash dividend of 2,320 million euros, equivalent to 33.21 gross euro cents per share, charged to 2025 profits, to be paid during the month of April.
And today we learned that Telefónica will cover 100% of the ERE in its three main subsidiaries with voluntary departures. The operator led by Marc Murtra has received a total of 5,123 requests for voluntary membership for the employment regulation files (ERE) in Telefónica de España, Telefónica Móviles and Telefónica Soluciones (the companies covered by the Related Companies Agreement, CEV), a figure that exceeds 100% of the 5,040 layoffs agreed in these three subsidiaries.
In addition, Indra’s board of directors has appointed Miguel Ángel Panduro as general director of the Space division, after closing the purchase of Hispasat. Panduro has extensive experience in telecommunications and defense.
The company also made headlines after signing an agreement with Nav Canada to supply air traffic training technology, according to Reuters. While, Expansion assures that Indra proposes that the Escribano give up power in the merger process.
In the analyst recommendations, good news for Aena, which sees Jefferies raising its advice from «hold» to «buy.» In addition, Citi maintains the ‘buy’ recommendation for Banco Santander and raises its target price to 11.90 euros, from the previous 10.
Already in the rest of Europe, a bullish close for the EURO STOXX 50 indicators gained 0.96% to 5,950 points, the CAC 40 advanced 0.68% to 8,126 points, the Dax revalues 1.06% to 24,550 points and el FT 100 with increases at the close of 0.56% to 10,228 points.
And on Wall Street, generalized falls for the indicators that, despite this, will end the month slightly positive. on the day when Donald Trump, eThe president of the United States nominated Kevin Warsh this Friday to succeed Jerome Powell as president of the Federal Reserve.
Despite the falls, the market has read his nomination well, that will have to pass the approval of Congress in order to succeed Powell next May. He is a former member of the Fed’s Board of Governors and that gives him a veneer of independence upon his arrival at the institution.
In terms of news, earnings presentations continue with Apple, Chevron and Exxon Mobil among them.
Apple posted earnings of $2.84 per share for the quarter, higher than the $2.67 per share expected by analysts. Revenue came in at $143.76 billion, significantly exceeding analyst expectations of $138.48 billion. Total iPhone revenue increased 23% year-on-year, reaching $85.27 billion.
And SANDISK stands out, which shoots up more than 22% after opening to the heat of your guides for the current quarter. The company expects fiscal third-quarter adjusted earnings of between $12 and $14 per share, versus analysts’ consensus of $5.11 per share. The fiscal second-quarter results also beat Wall Street estimates for gross and net income.
At the close of the Spanish market, the DOW JONES fell 0.63% to 48,762 points, the S&P 500 fell 0.41% to 6,940 points and the Nasdaq OMX fell 0.49% to 23,573 points.
If we look at what is happening in the rest of the market, we start with the fixed income market, with advances in the 10-year Spanish bond, from 0.50% to 3.216% while in the case of the German bund, there are increases of 0.51% to 2.8454%. The risk premium rises 2.35% and stands at 37.03 basic points.
In raw materials, oil is rising again after the early cuts and the accumulation of double-digit advances so far this year. He Brent barrel future presents gains of 0.46% to $69.93while West Texas places its price at $65.72, and gains 0.49%.
The Gold deserves a special mention, unleashed until yesterday so far this year. After a great bearish impulse with a collapse yesterday, it regained ground in the morning, to return to a strong bearish impact at this time with falls of 6.5% in the cash price and 5.65% in its futures, to $5,050 per ounce.
Despite this, its revaluation since the beginning of the year has reached 17%.
Already, Bitcoin is moving with drops of 2.6% to $83,067 per asset, while accumulating drops of 5.3% from the beginning of the year to the end of January.
Finally, in the Euro-Dollar relationship, we see how the greenback is recovering after the sharp falls that have led it to an exchange rate of more than 1.20 units this month against the single European currency. The community currency lost 0.69% to 1.1886 units.