
A wave of criticism and warnings about Tether’s current reserves has called into question the stability of USDT, the main stablecoin pegged to the US dollar.
These criticisms are fueled by a recent downgrade of its credit rating by S&P Global. The rating agency pointed out a risk of USDT price decline. But, Financial data from the company behind the stablecoin suggests a robust ability to face adverse scenarioseven prolonged crypto winters.
S&P Global’s recent rerating involved a move from 4 (limited) to 5 (weak), signaling an increase in perceived risk to the digital asset’s ability to maintain its peg to the dollar.
The analysis justified the negative revision by citing increased exposure to “high-risk assets,” such as bitcoin (BTC), in USDT reserves over the past year, and persistent gaps in information disclosure.
Composition of USDT reserves
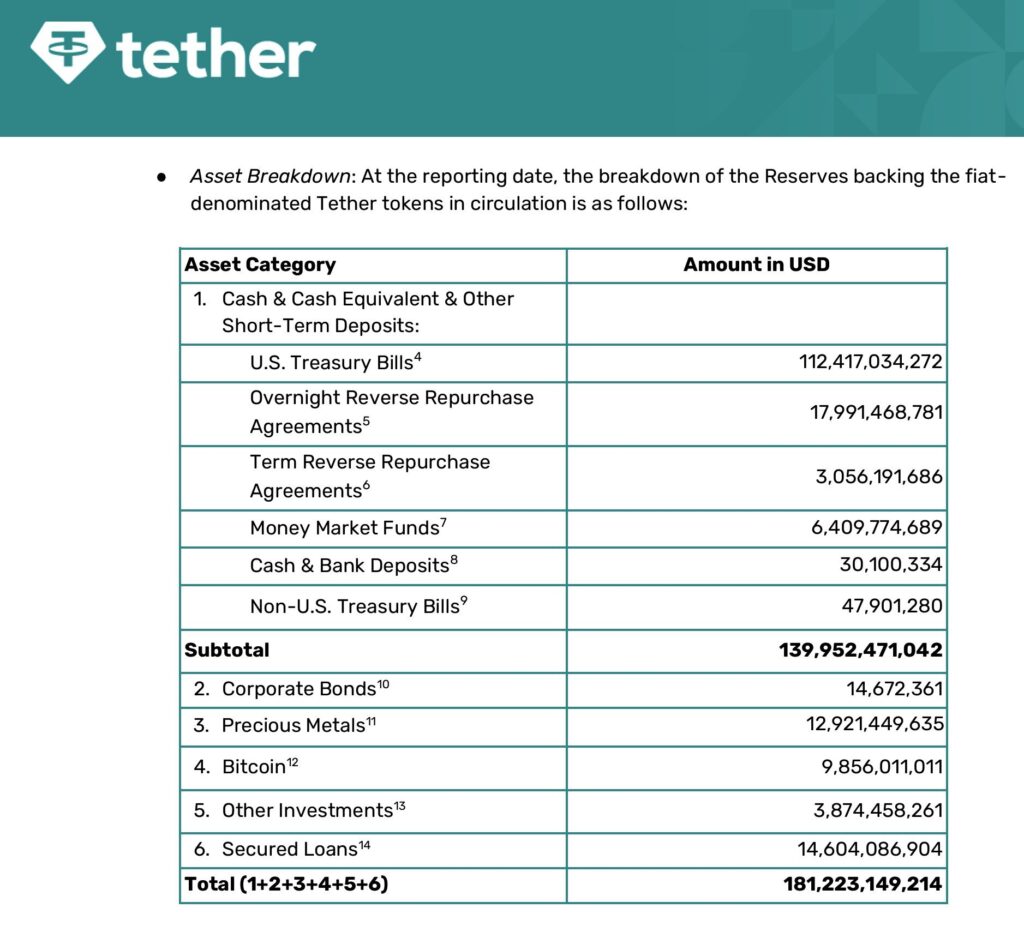
The audit at the end of Q3 2025 offers insight into the composition of current USDT reserves. The data shows that Tether holds 80.3% of its reserves in US Treasury bonds, 7.1% in gold and 5.4% in bitcoin.
With a total of 181,223 million dollars distributed in different assets within its reserve, until October 31. Reserves represent the assets backing the tokens in circulation, and slightly exceed the value of the issued tokens to maintain stability and cover risks. However, currently the circulating supply of USDT is already over 184.58 billion USDT and the total supply is around 186.956 million USDT.
The company has established itself as one of the largest global holders of US debt, surpassing countries like Germany. Its total holdings amount to $141 billion in Treasury-related assets. This figure is made up of $112,417 million directly in bonds and $27,457 million are placed in repurchase agreements and money market funds. These instruments are almost entirely backed by Treasury bonds.
This majority of the collateral in US debt instruments is considered low risk and high liquidity.
Likewise, the growing diversification towards assets such as gold is notable. Tether has 12,921 million dollars in precious metals (mainly physical gold) and $9.856 billion in bitcoin, which together represent more than 12% of the stablecoin’s total backing. For critics, this portion is excessive in a product that is advertised as “stable” and whose value must remain anchored to the dollar under any circumstances.
In fact, with 116 tons of the precious metal, its gold reserve is equal to those held by states such as Korea, Hungary and Greece, positioning itself as the investor with the most gold in the world, outside of central banks, as reported by NoticiasVE.
USDT Additional Capital and Arthur Hayes’ Criticism
Arthur Hayes, co-founder of the BitMEX exchange, questioned the financial soundness of Tether, arguing that diversification into gold and bitcoin is a hedging strategy that exposes them to a price drop.
Hayes warned that a roughly 30% drop in the combined value of gold and BTC could, in a hypothetical scenario, wipe out Tether’s capital, rendering USDT insolvent.
However, Paolo Ardoino, CEO of Tether, flatly rejected that analysis and explained that both Hayes and recent criticism (including the downgrade of S&P Global) are ignoring an essential part of the company’s balance sheet. In Ardoino’s own words, at the end of the third quarter of 2025 the company had $7 billion in excess capital above the stablecoin reserves and, additionally, another $23 billion in retained earnings that are part of the capital of the Tether Group.
This cushion, which is not reflected in the audit, It is a total of 30,000 million dollars that belongs entirely to the company and is not committed as a 1:1 backup of the tokens in circulation, so it acts as an extra layer of protection that is not being taken into account in the adverse scenarios raised by critics.
However, precisely by not appearing in the audits, a legitimate doubt arises as to whether these funds really exist in the declared magnitude or whether they could already be committed to other operations of the group. This opacity is one of the points that most fuels the recurring skepticism towards Tether.
Joseph Ayoub, a former Citi analyst, also defended Tether, but his argument strayed from the central issue. Instead of talking about the support of USDT, he focused on the profitability of the business. «Tether has approximately $120 billion in interest-bearing Treasury bonds […] That represents approximately $10 billion in net profit with little cost (150 employees), making it one of the most efficient cash-generating companies in the world.”
While it is true that Tether is profitable, this point does not address the main criticism of whether or not USDT reserves are fully backed 1:1 in an extreme stress scenario. The profitability of the parent company does not alone guarantee instant redemption of the tokens if a massive run occurs.
The resilience of USDT
The data presented so far allows us to infer that the robustness and diversification of USDT reserves today, together with its enormous cushion of surplus capital, allow it to face prolonged crypto winters.
Analysts like Ted Pillows remember that “Tether has been on the market for a decade and USDT is still at $1.00.” He added that while they operate with a fractional reserve model similar to that of traditional banks, stability is maintained «as long as repayments remain normal.»
Tether’s history includes going through moments of extreme market panic, such as the fall of Luna/Terra in May 2022. By the end of that year, even, slightly lost parity with the US dollar for a few hours, almost 2%reaching its lowest point around 0.98 per dollar. Despite this, the digital asset recovered in a short time.
This resilience is what has led analysts like Ayoub to point out that “Tether is not becoming insolvent, quite the opposite: they have a money printing machine,” Ayoub adds.
There are legitimate reasons for concern — S&P Global’s downgrade, growing exposure to volatile assets like bitcoin and gold, and continued opacity in the disclosure and actual existence of declared excess capital — but the risk of a USDT collapse remains low.
Therefore, until there is a massive and simultaneous loss of confidence combined with an extreme drop in bitcoin and gold prices, there is no solid evidence that USDT will break its peg with the dollar irreversibly in the short or medium term. Vigilance remains advisable, but panic is not justified with current data.