

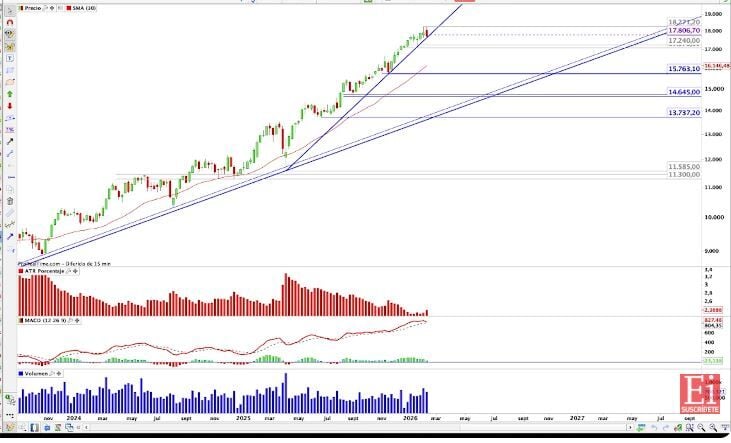
The Ibex 35 ends this Friday’s session below 17,700 points, specifically it has fallen 1.2%, to 17,672 points. . The Madrid selective has just accumulated three consecutive days of decline that have moved it away from the historical highs of 18,195.10 points that it achieved last Monday. In this way, it arrives at Friday’s session after having fallen 1.5% so far this week.
From a technical perspective, the fall «starts from an area of highs close to 18,270 points, where during this week a maximum of 18,267 was marked. It is evident that those historical highs from last year continue to function as a short-term resistance barrier,» says José Antonio González, technical analyst at Investment Strategies, and a weekly close below 17,806 points «would increase the probabilities that, in the coming weeks, we could see a correction towards the medium-term secondary growing guideline”.
Among the most penalized stocks of the session, Acerinox lost more than 4.5% and became the most penalized stock of the session. A day in which the stock markets have been watching precisely the steel companies after Donald Trump’s plan to reduce some tariffs on steel and aluminum products, according to the Financial Times, based on sources close to the matter. Senior officials at the Commerce Department and the US Trade Representative’s office believe the tariffs are hurting consumers by raising prices on products such as pie pans and cans of food and beverages. ArcelorMittal, which corrected strongly yesterday and became the most penalized value, ends the session with falls of more than 0.6%.
Bank actions follow Acerinox. Caixabank fell 4.5%, to 10.0150 euros, BBVA fell 3.4%. Above 19.1150 euros, Bankinter loses more than three percentage points while Santander shares correct more than 2.5%, so they will start on Monday at 10.028 euros. For its part, Banco Sabadell shares fell 2.5%. In the financial sector, Bankinter analysts have reiterated their ‘buy’ recommendation for Banco Santander and have raised the target price to 12.35 euros per share following the accounts presented by the bank at the beginning of the month. The valuation assumes an upside potential of more than 16% from current levels.
On the positive side, Cellnex is at the top of the Ibex 35 with increases of 2%, followed by Acciona and Repsol, which close with increases of more than one and a half percentage points.
In the continuous market, Aperam shares fell more than 3.5% while Adolfo Dominguez fell 2.6%. Positively, the strong increases in Tubos Reunidos stand out, closing the session with increases of more than 13%, followed by Nyesa Valores and Atrys Health, which rose more than 4%, respectively.
On the corporate side, JB Capital Markets cuts its recommendation on Enagás from ‘buy’ to ‘neutral’, while reducing the target price from 17.50 euros to 15.50 euros per share.
Without leaving the sector, Solaria has acquired 516 megawatt hours (MWh) in battery storage systems that will be installed in eight of its photovoltaic projects in Spain, bringing the total to 1,878 MWh in BESS acquired, with a total investment of 150 million euros. With this operation, the renewable group indicated that it «reinforces its strategy of vertical integration and optimization of renewable assets.»
This Friday, the European Commission gave the green light to the operation by which Aena Desarrollo Internacional, a subsidiary of Aena, takes over a majority stake in two international airports in the United Kingdom, Leeds Bradford (100%) and New Castle (49%), concluding that the operation will not have a negative impact on the European economic area. The Community Executive has concluded that the notified operation does not raise competition problems, because the companies do not operate in the same market or in vertically related markets and its impact on the European Economic Area is limited.
Investors are also paying attention to Repsol given the panorama that has opened up in Venezuela after the overthrow of Nicolás Maduro by the US a month ago. According to Bloomberg, Venezuela plans to award new exploration and production blocks to Chevron and Repsol in the coming days, within the framework of the Donald Trump administration’s plan to boost the participation of private capital in the recovery of the country’s energy sector. For its part, Reuters adds that the French Maurel & Prom would also be included.
In the Continuous Market, it must be taken into account that the Ordinary General Meeting of HBX Group International International has ratified the appointment of James Bilefield as director of the company, as reported to the CNMV.
In addition, PRISA has completed its buyback program after acquiring 1 million shares.
US CPI keeps Wall Street slightly up
On the macro agenda of the session, the CPI data for Spain was known right at the opening: The Consumer Price Index (CPI) cut its interannual rate in January by six tenths, to 2.3%, its lowest level since last June, due to the drop in fuel prices for personal vehicles and the evolution of electricity prices, according to the final data published this Friday by the National Institute of Statistics (INE).
Although the real protagonist, almost of the week, has been the CPI of the United States which has reached 2.4%, below forecasts and with an underlying that remains at 2.5%. A reference that has allowed Wall Street indices to open, reverse the trend and trade positively. At this time, the Dow Jones rises 0.2% above 49,580 points, the S&P 500 advances 0.3%, to 6,858 points and the Nasdaq 100 is trading at 22,683 points after registering increases of 0.3%. Even with the rise, the indices remain in negative territory for the week.
At the close, European stock markets maintain a mixed tone. He DAX closes with advances over 24,900 points, the FT-100 just over three tenths are scored, out of the 10,400 points, the CAc-40 gives up 0.3%, to 8,300 points, the Eurostoxx 50 falls just over two tenths and the FTSE MIB corrects just over one percentage point, over the 45,400 integers.
Raw materials, Currencies and other assets
In commodity markets, oil prices are turning lower again despite fears about a conflict between the United States and Iran that could affect supply having dissipated. International benchmark Brent oil falls 0.15% to $67.92 per barrel after exceeding $70 just a few days ago. US West Texas oil futures fell 0.54% to $62.58.
Gold rebounds after yesterday’s sharp fall, with a rise of 1.6% in its spot variety to reach $4,998. Silver rises 3.74% to $77.98.
The dollar continues to recover ground against the rest of the main currencies, with the Euro Dollar falling 0.07% against the greenback until leaving the exchange rate at 1.1863 dollars for each single currency.
In fixed income, The Spanish ten-year debt bond offers a return of 3.128% which leaves the risk premium against Germany at 37 points. On the other side of the Atlantic, the benchmark US ten-year bond pays 4.061% after the US CPI data.